Guarantor Home Loans: How Your Parents' Equity Can Help You Buy Your First Home

Written by Written by Victor Kalinowski, Mortgage Broker and Founder of Blackk
Written by Written by Victor Kalinowski, Mortgage Broker and Founder of Blackk


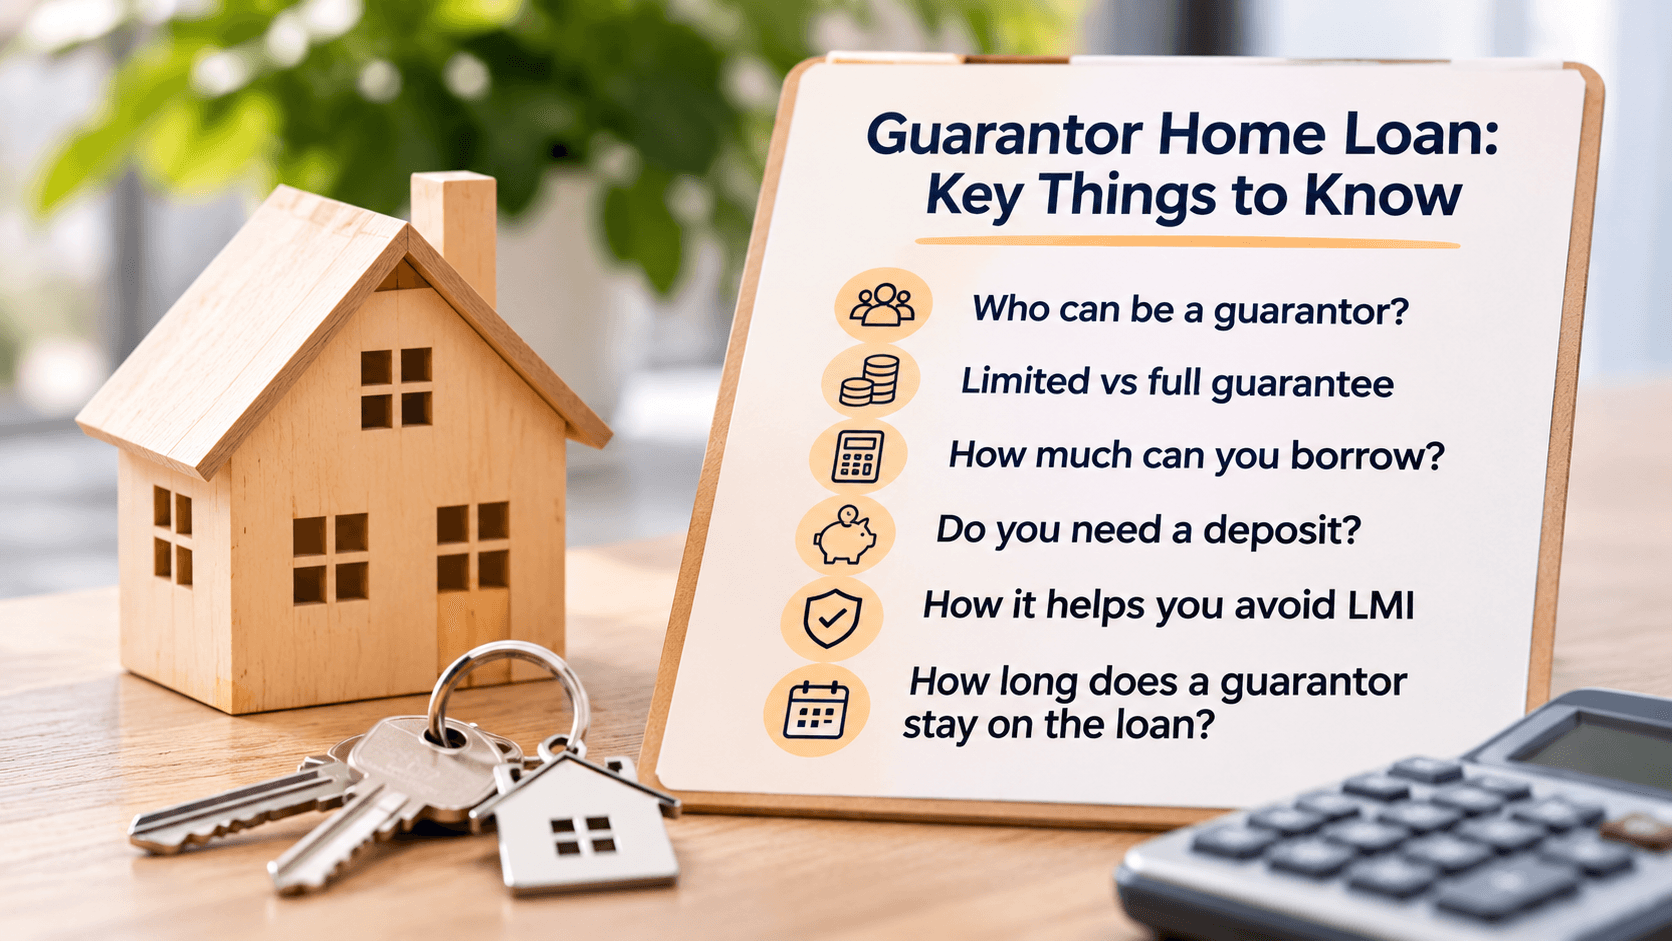
A family guarantor home loan allows a family member to provide a limited guarantee to support your home loan application.
In most cases, the guarantor secures the portion of the loan above 80% of the property's value. This allows you to purchase a home with a smaller deposit, or in some cases no deposit at all, while avoiding Lenders Mortgage Insurance (LMI).
Depending on the lender, a family guarantee can support borrowing up to:
- 100% of the purchase price, and
- Associated buying costs such as stamp duty and legal fees.
The maximum guarantee required depends on the purchase price, your available savings, and the lender's policy.
A full guarantee makes the guarantor responsible for the entire loan if the borrower cannot meet their repayments.
Full guarantees are more commonly seen with personal loans and car loans. For example let’s say that you provide a guarantee for your son to get a car loan to buy a car for $30,000. In this instance you are guaranteeing up too the full $30,000 of the car loan.
A limited guarantee is the structure most used for home loans.
In this arrangement:
- The lender is secured by the borrower's property up to 80% of the property's value.
- The guarantor only guarantees the portion above 80%.
- The guarantor's liability is limited to a specified amount outlined in the loan documents.
For example:
| Item | Amount |
|---|---|
| Property Value | $1,000,000 |
| 80% Loan Amount | $800,000 |
| Total Borrowing Required | $900,000 |
| Limited Guarantee Amount | $100,000 |
In this example, the guarantor's exposure is limited to $100,000 rather than the full $900,000.
The goal is usually to reduce and eventually eliminate the guaranteed portion through regular principal and interest repayments and as the homes value increases.
The answer depends on the lender's policy, but common guarantors include:
- Parents
- Step-parents
- Grandparents
- Adult children supporting parents
- Brothers and sisters
The stronger the guarantor's financial position, the more options are generally available.
Lenders will typically assess:
- Property ownership
- Equity in real estate
- Savings and investments
- Shares and managed funds
- Superannuation balances
- Employment status
- Income and financial commitments
A guarantor does not generally increase your borrowing capacity.
Your borrowing capacity is still assessed based on:
- Income
- Living expenses
- Existing debts
- Credit history
- The lender's servicing calculations
What a guarantor does is remove the need for a larger deposit and often eliminates the need for Lenders Mortgage Insurance (LMI).
In some situations, this can help borrowers who may not qualify for an LMI-backed loan due to previous credit issues or other circumstances.
Maybe.
A guarantor loan can potentially allow you to purchase with little or no deposit. However, lenders still want to see evidence of responsible financial behaviour.
If you don't have significant savings, the lender will usually want to understand where your money has been going over the previous 12 to 24 months.
Examples of acceptable financial behaviour might include:
- Consistently paying rent
- Rapidly reducing credit card balances
- Paying off personal loans
- Paying off car loans
- Reducing HECS-HELP debt
- Demonstrating strong cash-flow management
For example, if you've been paying $1,200 per week in rent for several years and your proposed home loan repayments are $1,100 per week, then the rent payment history can strengthen your application.
Lenders Mortgage Insurance is generally payable when you borrow more than 80% of the property's value.
A guarantor allows the lender to effectively split the loan structure:
- Up to 80% secured against the property.
- The amount above 80% secured by the family guarantee.
For example:
| Item | Amount |
|---|---|
| Property Value | $1,000,000 |
| 80% Lending Threshold | $800,000 |
| Total Borrowing Required | $900,000 |
| Family Guarantee | $100,000 |
Because the lender has additional security, LMI may not be required.
This can save many thousands of dollars in upfront costs.
The primary risk is that the borrower fails to meet their loan commitments.
If the borrower defaults:
- The lender may take action to recover the debt.
- The property may need to be sold.
- If the sale proceeds are insufficient to clear the debt, the lender could seek payment under the guarantee.
The real risk arises if the property's sale price is lower than the outstanding debt owed to the lender.
Several strategies can reduce risk:
Making extra repayments can reduce the guaranteed amount faster and shorten the period before the guarantee can be released.
Renovations and improvements that genuinely increase the property's value can help build equity faster.
Some guarantors choose to hold cash, investments, or other liquid assets equal to the guarantee amount.
For example, if a parent is guaranteeing $240,000, they may choose to keep at least that amount available in cash, shares, ETFs, or other accessible investments.
Avoid stretching borrowing capacity to the absolute maximum simply because a guarantor is available.
The guarantor usually remains in place until the loan balance falls below 80% of the property's value.
This can occur through:
- Regular loan repayments
- Extra repayments into the loan to pay it down.
- Property value growth
- A combination of the above.
Historically, we have generally seen guarantees released within approximately 2.5 to 3.5 years.
However, with flatter property markets (as it has been since May ’26) more borrowers are likely to achieve removing the family guarantees through debt reduction rather than relying on capital growth.
Once the loan balance is below 80% of the property's value, the borrower can request a review.
The lender will usually require:
- An updated property valuation
- Confirmation that repayments have been maintained satisfactorily
- A review of the current loan balance
If the lender is satisfied that the loan no longer requires the additional security, the guarantee can be removed.
A family guarantor loan offers several advantages over government support schemes.
- Can be used above government scheme property price caps.
- Can be available to borrowers who have previously owned property.
- Allows the borrower to retain 100% ownership of the property.
- Eliminates or reduces the need for a cash deposit.
- No family member needs to provide security.
- Parents do not place their property at risk.
- Suitable for eligible first home buyers within scheme limits.
The key difference is ownership.
- You own 100% of the property.
- The guarantor provides additional security.
- Family support helps bridge the deposit gap.
- The Australian Government contributes part of the purchase price.
- The government retains an equity interest in the property.
- Your ownership percentage is reduced until the government share is bought out.
Since the introduction of government assistance schemes, family guarantor loans have become less common.
Historically, around one in twenty first home buyer transactions we assisted involved a family guarantor arrangement.
We most commonly saw guarantor loans used when:
- The property exceeded scheme price caps.
- The borrower had previously owned property.
- The borrower was purchasing property from family members.
- The borrower wanted to avoid paying LMI.
Most guarantees we have seen fall within the range of:
The exact amount depends on:
- Purchase price
- Deposit available
- Associated buying costs
- Lender requirements
In addition to the guaranteed amount, there is usually a separate primary loan secured by the property itself.
In our experience, we have never had a client situation where a family guarantee was ultimately called upon.
The reason is that lenders still assess the borrower's ability to afford the loan before approval.
A family guarantee assists with the deposit position, but it does not replace serviceability requirements.
A guarantor loan may be a better option when:
Examples include:
- Regional Queensland purchases above the scheme limit.
- South East Queensland house purchases above approximately $1 million.
Many government support schemes require applicants to be first home buyers or meet strict ownership rules.
A guarantor loan may provide a solution where government assistance is unavailable.
Unlike shared-equity schemes, a guarantor loan allows you to retain 100% ownership of the property.
Usually not.
Most home loan guarantees are limited guarantees that only cover a specified portion of the borrowing rather than the entire debt.
Generally no.
In many cases, parents can leave their existing home loan exactly where it is.
The new lender simply registers an additional security interest against the guarantor property.
This is usually the biggest concern.
While it is possible in a worst-case scenario, the risk can often be managed through:
- Careful borrower assessment
- Maintaining financial reserves
- Limiting the guarantee amount
- Releasing the guarantee as soon as possible
This is a common concern for parents providing a guarantee.
If the borrowers separate after purchasing the property, disputes can arise regarding:
- Ownership of the property
- Responsibility for the debt
- Future repayments
- Sale proceeds
For this reason, it's often worthwhile for the borrowers to obtain legal advice and consider a formal legal agreement before purchase.
Having clear documentation in place before the loan is established can reduce uncertainty and help protect all parties involved.
A family guarantor home loan can be an effective way to help family members enter the property market sooner, avoid Lenders Mortgage Insurance, and purchase with a smaller deposit.
However, it is important that both the borrower and guarantor understand exactly how the guarantee works, the risks involved, and the pathway for removing the guarantee as quickly as possible. In most cases, the ideal outcome is to structure the guarantee, build equity through repayments, and have the guarantee released within the first few years of ownership.
One example we worked on involved clients who had saved approximately $140,000 and were looking to purchase a home on the Gold Coast in the $1.25 million to $1.30 million price range.
They ultimately purchased a property for $1.24 million. Rather than using all of their savings toward the purchase, they wanted to retain $10,000 as a financial buffer after settlement.
To achieve this, the loan was structured as follows:
| Component | Amount |
|---|---|
| Purchase Price | $1,240,000 |
| Main Home Loan (80%) | $992,000 |
| Family Guarantee Amount | $172,000 |
| Total Lending | $1,164,000 |
| Savings Contributed | $130,000 |
| Savings Retained After Settlement | $10,000 |
In this scenario, the borrowers contributed $130,000 from their savings and retained $10,000 in reserve for unexpected expenses after moving into the property.
The parents provided a limited family guarantee of $172,000, secured against their own property. The borrowers also took out a standard home loan of $992,000, representing 80% of the purchase price.
This structure provided several benefits:
- The borrowers were able to purchase the home they wanted without exhausting all of their savings.
- They retained a cash buffer after settlement.
- They were able to avoid paying Lenders Mortgage Insurance (LMI) (without the Family Guarantee the cost of LMI would have been $50,800 + as an example in this situation)
- The parents' guarantee was limited to $172,000, rather than the full loan amount.
- The borrowers maintained 100% ownership of the property.
As the borrowers make principal and interest repayments and reduce the overall debt, the guaranteed amount becomes less risky. Once the loan balance falls below 80% of the property's value, the family guarantee may be eligible for release, subject to the lender's assessment and an updated valuation.
This is a good example of how a family guarantor arrangement can help buyers access a higher-priced property while preserving some savings and avoiding LMI, without requiring parents to guarantee the entire home loan.

Victor Kalinowski
Mortgage Broker and Founder of Blackk
I’m Victor Kalinowski and a Brisbane Mortgage Broker at Blackk Mortgage Brokers. I’ve helped thousands of people get loans for their homes and investment properties.


99.9% Approval Rate
Insider advice to negotiate making a successful offer on a home

Award Winning Mortgage Broker
If you are happy with the service from your current lender, but would like a better deal.

Work with Victor, not with random brokers
If you are happy with the service from your current lender, but would like a better deal.
with 99.6% first time success rate
No Obligations

Subscribe to get tips on home loans and property straight to your inbox
By downloading you agree to receiving occasional and only useful emails from us.

