How to Pay Off Your Mortgage Faster

Written by Written by Victor Kalinowski, Mortgage Broker and Founder of Blackk
Written by Written by Victor Kalinowski, Mortgage Broker and Founder of Blackk


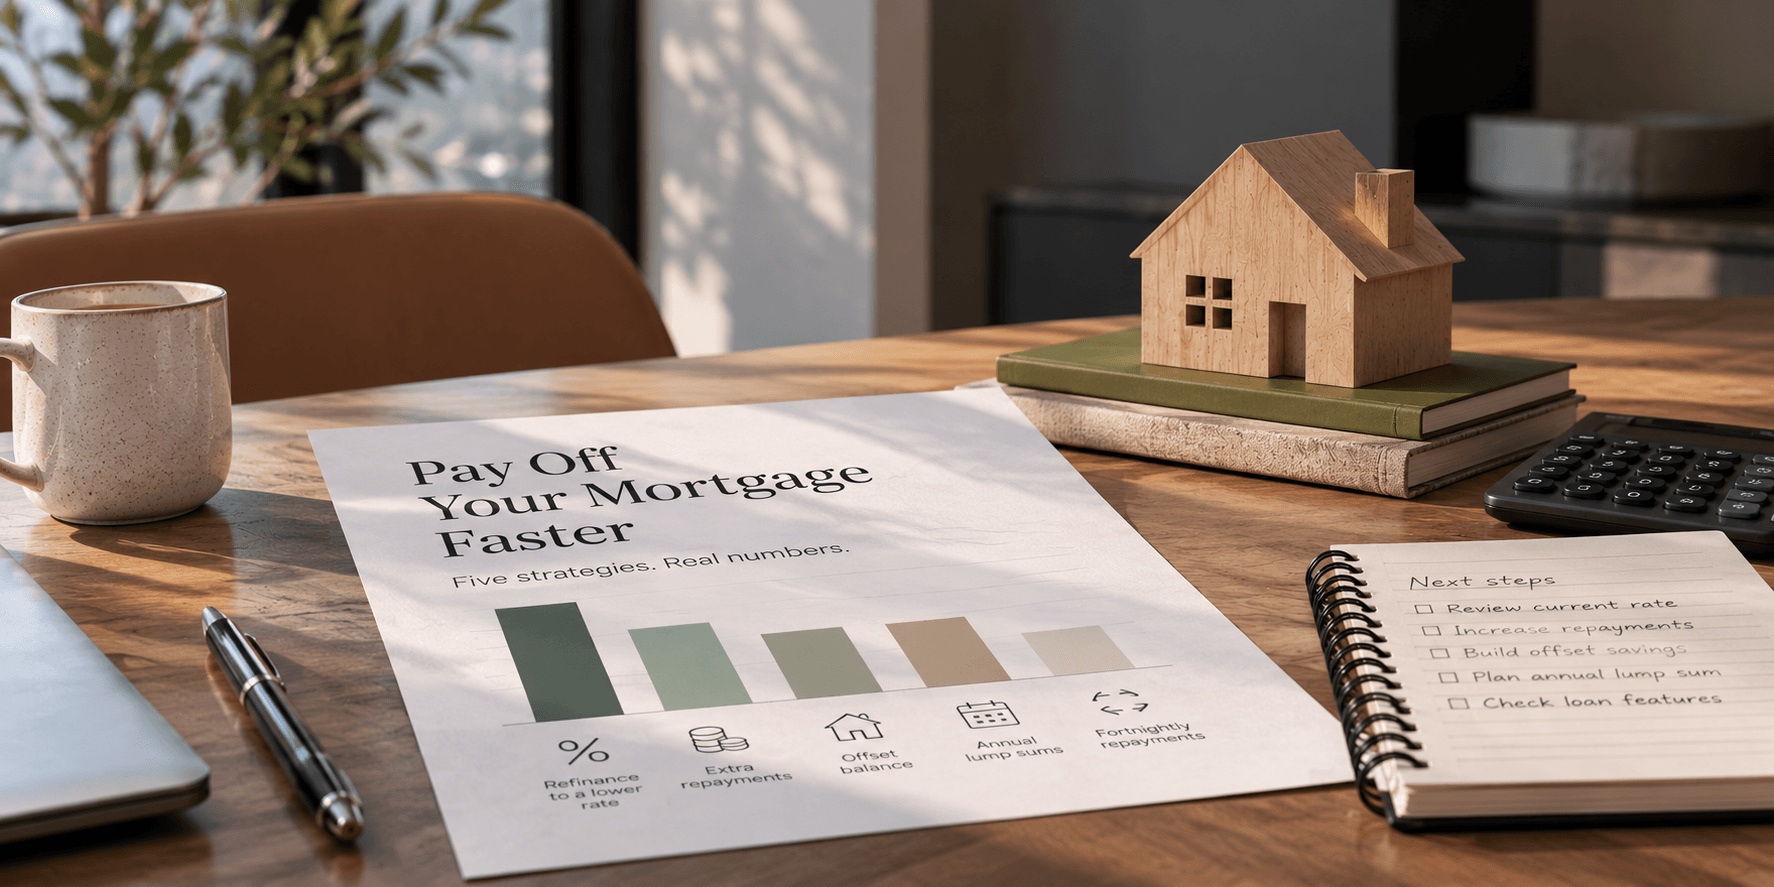
A 30-year home loan takes 30 years if you only ever pay the minimum. Depending on the strategy, these five changes could cut roughly four and a half to seven years from the worked example below. Combining them can shorten the term further. We'll compare all five on a real Brisbane loan below, show the maths, and tell you which one to pull first based on your situation.
Every number below runs off one worked example, so you can compare like for like.
- Loan amount: $650,000
- Term: 30 years
- Rate: 6.19% p.a. variable, principal and interest
- Repayment type: monthly
The 6.19% figure is the RBA's July 2026 average for outstanding owner-occupier P&I loans. New loans averaged 6.16%. At 6.19% over 30 years, the monthly repayment is roughly $3,979 and total interest paid comes to about $782,600. You pay the house back more than twice over.
If your numbers are different, model your own repayments and see where you land. The same strategies can be modelled across different loan sizes, although the exact savings will vary. The dollar figures scale with your balance.
Here is what each strategy does on the $650,000 worked example. They are shown side by side rather than ranked because the strongest option depends on whether you value interest savings, liquidity or the shortest possible loan term.
These figures are indicative and assume the strategy starts immediately and continues for the remaining life of the loan. The refinancing estimate excludes switching fees, while the offset calculation assumes an average balance of $50,000 is maintained. Your lender’s calculation may vary.
Refinancing tops the list because a rate cut compounds over 25-plus years. Moneysmart's switching home loans guide notes there can be more than a 2% difference in variable rates on the market at any given time. On this $650,000 example, reducing the rate from 6.19% to 5.19% and continuing to pay about $3,977 per month would cut roughly six years and three months from the loan and save about $301,000 in interest before refinancing costs.
A lower rate affects the entire outstanding balance, which is why even a one-percentage-point reduction can make such a large difference over a long loan term.
Moneysmart also points out that borrowers with at least 20% equity have real bargaining power. That's the moment to either ask your current lender for a better deal or start shopping. If you haven't reviewed your rate in the last two years, this is the lever to pull first. Refinancing your home loan isn't always the answer, but it's worth checking every couple of years at minimum.
An additional $100 a week, or about $433 a month, would save approximately $207,000 in interest on the worked example and repay the loan about six years and ten months earlier. The early years matter most, because that's when interest makes up the biggest slice of every repayment. An extra dollar paid in year two does more work than the same dollar paid in year 20.
Lump sums stack on top. Putting a $5,000 lump sum into the loan at the end of every year would save approximately $194,000 in interest and shorten the term by about six years and five months. Add it to weekly extras and the numbers compound.
One watch-out. If you're on a fixed rate, many lenders limit how much extra you can pay during a fixed-rate period, and break costs may apply if you repay the loan early. We cover this in more detail in our piece on fixed rate extra repayment caps. If you're on an investment loan, the tax deductibility angle changes the maths, so speak to your accountant before you pour money into the principal.
Putting a $5,000 lump sum into the loan at the end of every year would save approximately $194,000 in interest and shorten the term by about six years and five months. Tax refunds, bonuses and other windfalls can have a larger effect when they are paid into the loan early in the term.
With fortnightly repayments, the saving comes from paying half the monthly amount every two weeks. Over 26 fortnights, that adds up to the equivalent of 13 monthly repayments rather than 12. On the worked example, this would reduce the term by approximately five years and seven months and save about $172,000 in interest.
There is also a practical benefit when repayments coincide with payday because the additional amount is transferred automatically. One drawback is that fortnightly payments may create a cashflow mismatch for people paid monthly, so check the timing against your budget before switching.
An offset account is a transaction account linked to your loan. The balance reduces the loan amount that interest is calculated on. Moneysmart's worked example puts it simply. A $500,000 loan with $20,000 sitting in the offset means you're only charged interest on $480,000.
The reason offset beats extra repayments for a lot of borrowers is liquidity. The money is still yours. You can pull it out for a car, a renovation or a rough month. Extra repayments made straight to the loan may need to be redrawn, and not every lender makes that easy.
An offset account can still cost more than it saves if the balance remains low or the loan carries a higher rate or additional package fees. Moneysmart notes that an offset feature may not be worth paying for if your balance usually stays below $10,000. Getting the setup wrong is expensive too. Moneysmart's offset accounts guide gives an example of a $750,000 loan over 30 years with a $50,000 average offset balance at 6.25%. If the offset wasn't actually linked, the borrowers paid over $3,000 extra interest in a single year, would have lost nearly $230,000 over the life of the loan, and would have added four years to their term.
We break the mechanics down further in how offset accounts work.
Plug your balance, rate and repayment into our home loan repayments calculator and see what each lever is worth to you. No signup, no follow-up call unless you ask for one.
The calculations provide a useful comparison, although the most suitable starting point depends on your loan, income and need for access to cash.
- You haven't reviewed your rate in two or more years: refinance first. Everything else is a smaller lever pulled on a bigger-than-necessary balance.
- You have irregular income (self-employed, commission, bonuses): offset first. Keep the liquidity. Extra repayments lock the money away.
- You have a tax refund or bonus coming: lump sum. Straight to principal in the early years pays back for decades.
- You're on a fixed rate: check your annual extra repayment cap before adding anything. Break costs can outweigh the savings.
- Cashflow is tight right now: fortnightly alignment, or look at reducing your repayments if cashflow is tight before you try to accelerate. There's no point overpaying if it forces credit card debt.
Most borrowers we speak to end up combining two or three levers. A borrower might refinance, move to fortnightly repayments and keep an emergency fund in an offset account. Used together, those changes can remove considerably more time from the loan than any one strategy used alone.
Paying the mortgage down isn't always the smartest use of a dollar. A few honest exceptions.
You've got no emergency buffer. Money paid into the loan is hard to get back at short notice. Build three months of expenses in offset before you accelerate.
You have higher-interest debt. Credit cards at 20% and car loans at 9% should be cleared before you tip extra into a 6% mortgage.
It's an investment property. Interest may be deductible to the extent that the borrowed money is used to produce assessable income. The treatment depends on how the loan and any redrawn funds are used, so get tax advice before changing the balance. Paying it down faster can reduce your deductions. Talk to your accountant on this one, not just your broker.
You're in a cashflow season, not an affordability problem. Daycare, a renovation, a year of school fees. These are temporary. If your debt-to-income ratio is fine but the month feels tight, the fix is usually restructuring for that season, not selling the house or draining the savings into the loan.
The RBA cash rate was 4.35%, effective 12 August 2026, with the next update scheduled for 29 September 2026. The cash rate flows through to mortgage rates over time, though not always immediately or fully.
A rate reduction can also create an opportunity to pay the loan down faster. When rates fall, most lenders drop your minimum repayment. If you keep repaying the old amount, the extra goes straight to principal. If the rate on the worked example fell from 6.19% to 5.69% and the borrower continued paying approximately $3,977 per month, the loan would finish about three years and eight months earlier. This assumes the lender passes on the full reduction and the rate remains unchanged.
We wrote more about how rate changes affect your loan if you want the details.
FAQs
Yes, although the required repayment depends on the balance and interest rate. On this example, combining a one-percentage-point rate reduction, an extra $100 a week and a $5,000 annual lump sum would reduce the term to approximately 17 years. Reaching 15 years would require a larger regular repayment, larger lump sums or a lower rate.
An offset may suit borrowers who want to reduce interest while keeping their savings accessible. You get the same interest saving with the money still available if you need it. Extra repayments only win if you're certain you won't touch the money and your lender doesn't charge for the offset feature on small balances.
Yes, because you end up paying 13 months' worth every year instead of 12. On the worked example, paying half the monthly amount every fortnight would save approximately five years and seven months and about $172,000 in interest.
Variable-rate loans generally allow additional repayments, although fees and redraw conditions vary. Fixed-rate loans may impose repayment limits or break costs, so check the contract before making a large payment.
On the worked example, approximately $207,000 in interest, with the loan ending about six years and ten months earlier.
Depends on your rate, your tax situation and your risk tolerance. Putting money into a mortgage charging 6% avoids interest at the current loan rate. That is a certain saving while the rate remains at 6%, although it is not the same as earning a 6% investment return. Investing might beat it, might not. Our full refinance guide covers the trade-off in more detail.
Want us to run these numbers on your loan?
A 20-minute call with Victor Kalinowski gets your actual loan modelled against these five levers. Victor's been doing this since 2007. 19-plus years in lending means he'll spot the two or three moves that make the most difference for your situation, not read off a checklist.
No cost, no obligation, no follow-up unless you want one. Talk to a Brisbane mortgage broker when you're ready.
References

Victor Kalinowski
Mortgage Broker and Founder of Blackk
I’m Victor Kalinowski and a Brisbane Mortgage Broker at Blackk Mortgage Brokers. I’ve helped thousands of people get loans for their homes and investment properties.


99.9% Approval Rate
Insider advice to negotiate making a successful offer on a home

Award Winning Mortgage Broker
If you are happy with the service from your current lender, but would like a better deal.

Work with Victor, not with random brokers
If you are happy with the service from your current lender, but would like a better deal.
with 99.6% first time success rate
No Obligations
99.9% Approval Rate
Insider advice to negotiate making a successful offer on a home
Award Winning Mortgage Broker
If you are happy with the service from your current lender, but would like a better deal.
Work with Victor, not with random brokers
If you are happy with the service from your current lender, but would like a better deal.
with 99.6% first time success rate
No Obligations

Subscribe to get tips on home loans and property straight to your inbox
By downloading you agree to receiving occasional and only useful emails from us.

